The intelligence layer for regime-aware portfolios.

A rules-based, regime-aware quantitative portfolio engine, licensed to your brokerage's PMS, advisory, and HNI client desks. We build the intelligence layer — you keep onboarding, suitability, custody, and execution.

Connect with us

THE PROBLEM

Widening gaps in Indian wealth management.

Widening gaps in Indian wealth management.

Limited access

Locked-Out Investor Base

PMS requires 50 lakh and AIF requires 1 crore minimum ticket sizes

Static portfolios

Risk persists across market cycles

Traditional portfolios maintain fixed allocations regardless of changing market conditions, leaving investors exposed to avoidable drawdowns

Black-box strategies

Little transparency

Many algorithmic strategies offer limited insight into how positions are selected. risks are managed, or decisions are made

High in-house cost

Unaffordable R&D

Building a quant research team requires significant capital, technology and expertise, putting advanced portfolio intelligence beyond the reach of most wealth managers

OUR APPROACH

A four-step market regime engine.

A four-step market regime engine.

01

Regime detection engine

Evaluates market conditions daily across four states. PersistUP, NORMAL, PersistDOWN, TURBO, using rules-based trend, volatility, breadth, and momentum metrics

02

Dynamic universe selection

Filters the NSE/BSE universe by regime: growth and momentum in risk-on, defensive tilts in balanced, gold, bonds and cash in risk-off.

03

Risk-aware optimizer

Maximizes risk-adjusted return while imposing minumum holding periods to curb overtrading.

04

Automated signal delivery

Daily rebalance signals delivered by API into PMS and broker execution engines, with complete audit

01

Regime detection engine

Evaluates market conditions daily across four states. PersistUP, NORMAL, PersistDOWN, TURBO, using rules-based trend, volatility, breadth, and momentum metrics

03

Risk-aware optimizer

Maximizes risk-adjusted return while imposing minumum holding periods to curb overtrading.

02

Dynamic universe selection

Filters the NSE/BSE universe by regime: growth and momentum in risk-on, defensive tilts in balanced, gold, bonds and cash in risk-off.

04

Automated signal delivery

Daily rebalance signals delivered by API into PMS and broker execution engines, with complete audit

WHY IT MATTERS FOR YOU

A glass-box, auditable quant model.

a shared

₹5L Ticket Size


Operates at full model fidelity starting at ₹5 lakh

100% Audit Ready


Every signal and allocation weight is traceable, explainable and SEBI compliance-friendly

AI-Assisted Engineering


AI accelerates software development and operations. All investment decisions comes from rules-based models

OUR PERFORMANCE

Our strategy vs. NIFTY 50

BACKTESTED PERFORMANCE | 6.5 YEARS | 1,629 TRADING DAYS

Metric

Our Strategy

NIFTY 50

CAGR (gross)

CAGR (gross)

44.82%

11.15%

Sharpe ratio (gross)

Sharpe ratio (gross)

2.07

0.62

Sortino ratio

Sortino ratio

2.79

0.73

Max drawdown

Max drawdown

-24.93%

-37.93%

Calmar ratio

Calmar ratio

1.80

0.30

Win rate

Win rate

58.0%

—

Beta vs NIFTY 50

Beta vs NIFTY 50

0.78

1.00

Alpha (annualised)

Alpha (annualised)

+29.93%

—

Net of trading costs (70bps round-trip — STT, brokerage and market impact): CAGR 27.42%, Sharpe 1.24, One-year rolling Sharpe ranges -0.05 to 6.34 (mean 2.27), shown for stability rather than a single cherry-picked number. Backstested results are not a guarantee of future performance.

Growth of ₹10,000 | 2020 - 2026

₹10,000 grew to ₹1,10,575 vs ₹19,800

₹10,000 grew to ₹1,10,575 vs ₹19,800

Regime detection adds the edge: PersistUP CAGR +57.2% vs NIFTY +21.0%; NORMAL +62.5% vs +11.2%; PersistDOWN -0.5% vs -13.5%. Capital is preserved in downturns, not just grown in rallies. Curve is indicative between verified start and end values.

Live forward testing | Interactive Broker

Metric

Client A

Live since

Live since

May 5, 2026

May 5, 2026

Elapsed period

Elapsed period

~15.7 weeks

~15.7 weeks

Cumulative return

Cumulative return

10.40%

10.40%

Max drawdown (live)

Max drawdown (live)

-6.41% (recovered in 9 days)

-6.41% (recovered in 9 days)

NIFTY 50 since inception

NIFTY 50 since inception

1.98%

1.98%

Sharpe ratio (live)

Sharpe ratio (live)

1.73 (NIFTY 0.17)

1.73 (NIFTY 0.17)

Annualised figures are withheld — the window is too short to annualise honestly.

WHAT WE DO DIFFERENT

The only pure cash, long-only, no margin, no futures & options, quant momentum engine

The only pure cash, long-only, no margin, no futures & options, quant momentum engine

An AIF/SIF-grade quant model licensed to SEBI-registered PMS partners for execution. No F&O, full equity upside, at a partner ticket accessible to a far wider set of Indian investors.

Structure

Structure

Category III AIF

Category III AIF

Quant AIF

Quant AIF

Multi-asset PMS

Multi-asset PMS

Tactical derivates

Tactical derivates

VectoQuant

VectoQuant

Minimum investment

Minimum investment

₹1 CR+

₹1 CR+

₹1 CR+

₹1 CR+

₹50 L

₹50 L

~1₹ CR+

~1₹ CR+

₹5 L

₹5 L

Direct equity ownership

Direct equity ownership

No, pooled structure

No, pooled structure

No, pooled structure

No, pooled structure

Partial, blended with debt/gold

Partial, blended with debt/gold

No, derivative based

No, derivative based

Yes, fully equity upside

Yes, fully equity upside

Relies on F&O for alpha

Relies on F&O for alpha

Yes, built in by mandate

Yes, built in by mandate

Yes, core to the model

Yes, core to the model

No, but diluted by other assets

No, but diluted by other assets

Yes, spread dependent

Yes, spread dependent

No F&O exposure

No F&O exposure

Rebalancing

Rebalancing

Manager discretion

Manager discretion

Model-driven, AIF cadence

Model-driven, AIF cadence

Slower, multi-asset cadence

Slower, multi-asset cadence

Spread driven, short horizon

Spread driven, short horizon

Weekly, factor-triggered

Weekly, factor-triggered

Regulatory Load

Regulatory Load

Heavy, full Cat III compliance

Heavy, full Cat III compliance

Heavy, full Cat III compliance

Heavy, full Cat III compliance

Standard PMS

Standard PMS

Standard mutual fund

Standard mutual fund

Licensed to SEBI-registered PMS aprtners

Licensed to SEBI-registered PMS aprtners

Who it's actually built for

Who it’s actually built for

Investors wanting hedged, complex exposure

Investors wanting hedged, complex exposure

UHNI tickets that can absorb derivative risk

UHNI tickets that can absorb derivative risk

Investors prioritzing smoothness over upside

Investors prioritzing smoothness over upside

Investors chasing spread income, not equity growth

Investors chasing spread income, not equity growth

Investors who want pure momentum at a lower ticket

Investors who want pure momentum at a lower ticket

WHO WE ARE

The people behind the engine.

The people behind the engine.

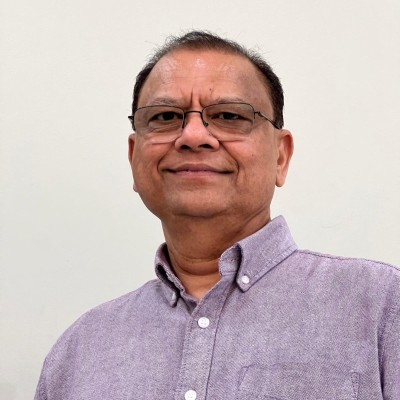
Tushar Bhavsar | Founder & CTO

With 25+ years of experience at Pfizer leading global systems integration, ERP architecture, and digital transformation in highly regulated environments, Tushar brings a systems-driven approach to financial technology. At VectoQuant, he applies that experience to building transparent, rules-based portfolio intelligence designed to make institutional-grade quantitative tools more accessible to investors, advisors, and asset managers.

BROKER PARTNERSHIP

License the engine. Keep the client.

License the engine. Keep the client.

We work with SEBI-registered brokerages, PMS providers and advisory desks. Onboarding, suitability, custody, and execution remain entirely yours.

Connect with us

VectoQuant India LLP is a quantitative technology provider. We build and license research-driven portfolio models to SEBI-registered partners — PMS providers, advisers and brokerages — who retain full responsibility for client suitability, custody and execution. Backtested and forward-tested results are indicative of model behaviour in past conditions rather than of future performance, and investments in securities remain subject to market risk.

© 2026 VectoQuant India LLP